








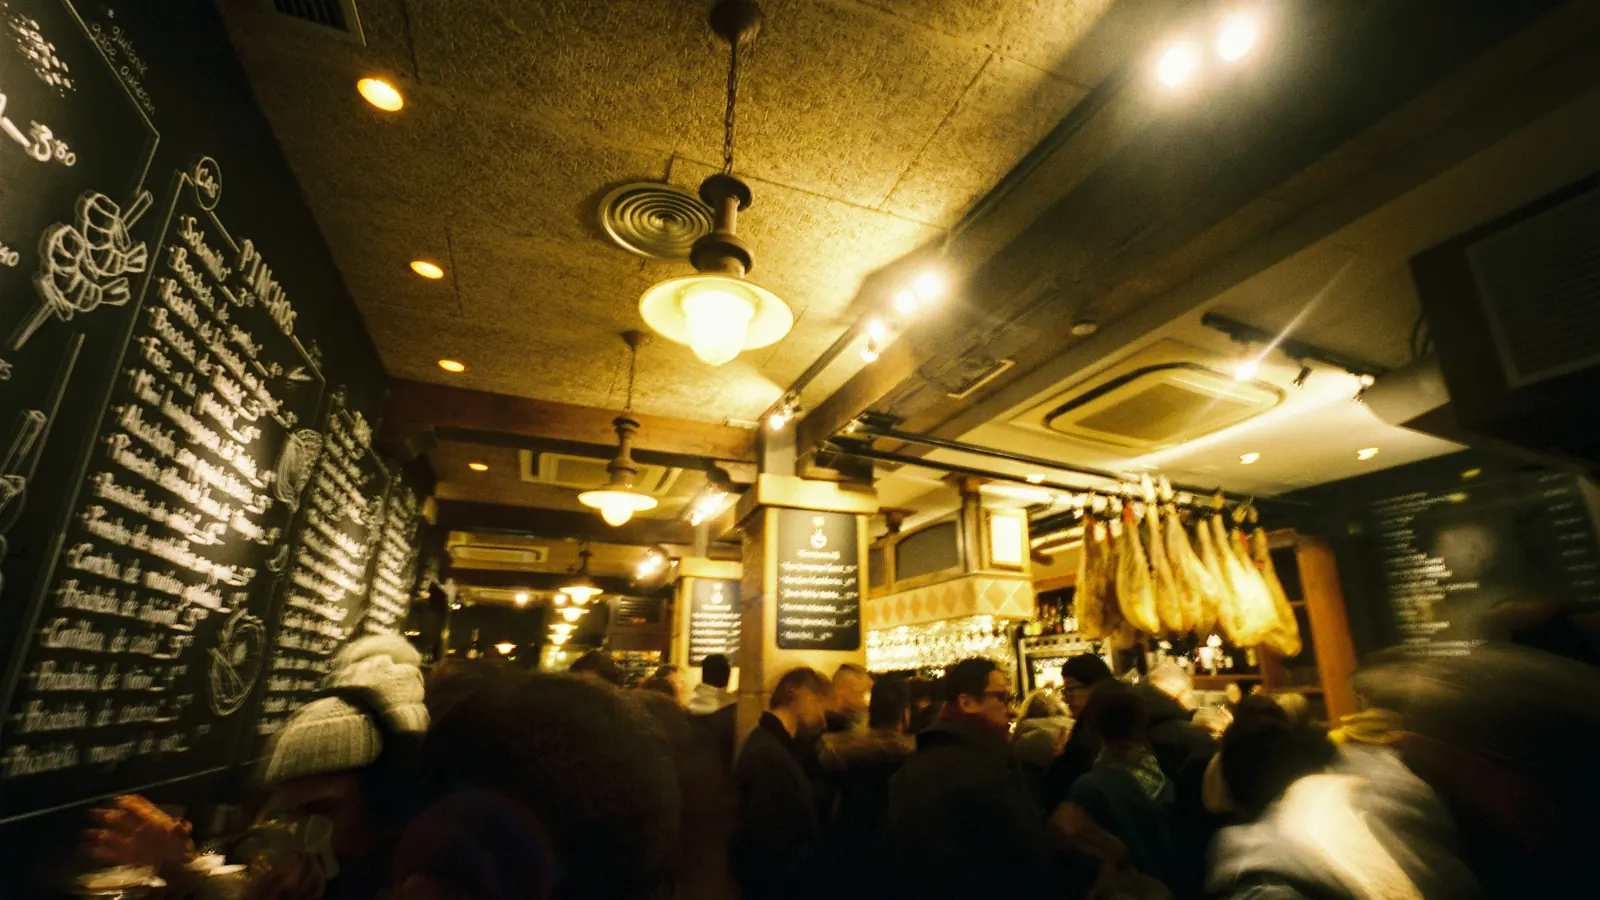


A bar in Spain with two full-time employees on the 2026 minimum wage carries a payroll of €44,667 a year once employer social security is added, before rent, stock or the first coffee is served. The demand side is strong: international tourists spent €114,380 million in Spain between January and September 2026, 8.0% more than a year earlier, according to the National Statistics Institute (INE) tourist spending survey.
Key points:
- Spain received 80.5 million international tourists in the first nine months of 2026 (+5.2%), after a record 96.8 million in 2025.
- The minimum wage is €1,221 a month, with an annual floor of €17,094; employer contributions for a permanent worker add 30.65%, before the occupational-accident premium.
- Bars are not on the state list of activities freed from a prior licence: the opening procedure is set by each town hall and autonomous community.
Why Spain, why now
Tourism keeps feeding the counter. INE's border survey counted 96.8 million international tourists in 2025, the highest figure in its series, and the spending survey put their outlay at €134,712 million, up 6.8%. The trend continued in 2026: 80.5 million arrivals to September, 5.2% more than in the same months of 2025, according to the September 2026 release.
Food and drink is a line of its own in that spending. In September 2026 alone, international tourists spent €2,263 million on meals and drinks outside package holidays, 15.6% of their total and 6.9% more than in September 2025.
The tax treatment of what a bar sells is stable: Article 91 of the VAT Law 37/1992 applies the reduced 10% rate to hospitality and restaurant services and, in general, to food and drinks served for consumption on the spot.
The competition is large and fragmented. INE's Central Business Directory recorded 266,476 active hospitality companies on 1 January 2025, 8.0% of the 3,310,824 companies in Spain. Of these, 63,063 had no employees and 106,638 had one or two: 63.7% of the sector, by our calculation, works with two employees or fewer. The figure covers both accommodation and food and drink service.
The numbers: a bar with two employees
Our calculation, built only on official rates. Hypotheses: a limited company (SL) employs two people full time on permanent contracts, paid the minimum wage; the bar opens 310 days a year.
- Wages: Royal Decree 126/2026 sets the minimum wage at €40.70 a day or €1,221 a month, and no annual amount below €17,094. Two employees: €34,188.
- Employer contributions: the Social Security 2026 rates charge the employer 23.60% for common contingencies, 5.50% for unemployment on a permanent contract, 0.20% for the wage guarantee fund (FOGASA), 0.60% for vocational training and 0.75% for the intergenerational equity mechanism (MEI): 30.65%, or €10,478.62. The occupational accident and disease premium, which depends on the activity code, is not included.
- Payroll cost: €44,666.62 a year.
- Takings needed to cover payroll alone: with 10% VAT on top, €49,133.28 at the till, or €158.49 a day over 310 days. Rent, stock, energy and the owner's own pay come on top.
- Corporate tax: under Article 29 of the Corporate Income Tax Law 27/2014, a newly created company carrying out an economic activity pays 15% in its first year with a positive tax base and the following one. On €30,000 of profit that is €4,500, against €5,700 under the 2026 scale for companies with turnover below €1 million (19% on the first €50,000). The 15% rate does not apply when the activity was previously run by a related person and transferred to the new company.
- Business tax (IAE): companies with net turnover below €1 million are exempt, under Article 82 of the Local Finance Law.
- Capital: an SL can be set up with €1, under Article 4 of the Capital Companies Law; until capital reaches €3,000, at least 20% of profit goes to the legal reserve, and in a liquidation the partners answer jointly for the difference up to €3,000.
How it is done
- The company. Article 15 of Law 14/2013 on support for entrepreneurs allows an SL to be incorporated with a standard deed and model articles through the electronic single document (DUE) and the CIRCE system, at an entrepreneur service point. The registrar must register the company within six business hours of receiving the deed. A self-employed owner can instead claim, under Article 38 ter of the Self-Employment Statute, a reduced contribution for the first twelve months; the amount is set in the State Budget Law.
- The premises. Law 12/2012 frees the retail activities listed in its annex, in premises of up to 750 square metres, from a prior municipal licence. The annex follows the business tax headings and does not include bars and cafés. The procedure (licence or responsible declaration), noise and opening-hour rules for a bar are therefore those of the town hall and the autonomous community where it opens.
- Staff. Each employee is registered with Social Security before starting work, at the rates above.
- Tax registration. The company registers in the tax census and charges 10% VAT on what it serves.
What can go wrong
- The wage is a floor. Article 2 of Royal Decree 126/2026 adds to the minimum wage the salary supplements set by collective agreements and contracts: the payroll above is the minimum, not the market rate for the sector.
- Spending is concentrated. In the first nine months of 2026, Catalonia took 18.9% of international tourist spending, the Balearic Islands 17.0% and the Canary Islands 15.8%. A bar outside the main destinations works on local demand.
- Seasonality. Spain received 10.1 million international tourists in September 2026 and 5.3 million in December 2025.
- Costs are rising. Consumer prices rose 4.9% in the year to October 2026, and the housing group, driven by gas and electricity, rose 7.6%, according to the INE consumer price index.
- Municipal timing. Because the licence regime is local, the time between signing a lease and opening depends on the town hall.
Spain and Italy compared
Both countries tax drinks served at the bar at 10% VAT. The entry rules differ: in Italy, Article 71 of Legislative Decree 59/2010 requires the owner or a designated manager to hold a professional qualification for food and drink service (a regional course, two years of experience in the sector in the last five, or a relevant diploma). On the tax side, a new Spanish SL pays 15% on its first profitable years, against the 24% of Italy's corporate income tax (IRES), set by Article 77 of the Italian Income Tax Code.
Spain's tax and social security figures can be compared with the other 21 countries in our relocation comparator, on the Spain country page and in the guide to starting a business abroad.
Sources
- INE, Tourist Spending Survey (EGATUR), September 2026
- INE, Border Tourist Movements (FRONTUR), September 2026
- INE, FRONTUR, December 2025 and year 2025
- INE, EGATUR, December 2025 and year 2025
- INE, Central Business Directory (DIRCE), 1 January 2025
- INE, Consumer Price Index, October 2026
- Royal Decree 126/2026 on the 2026 minimum wage, Articles 1 to 3 (BOE)
- Social Security, contribution bases and rates 2026
- Law 37/1992 on VAT, Article 91 (BOE)
- Law 27/2014 on Corporate Income Tax, Article 29 and transitional provision 44 (BOE)
- Capital Companies Law, Article 4 (BOE)
- Law 14/2013 on support for entrepreneurs, Article 15 (BOE)
- Law 12/2012 on the liberalisation of retail trade, Article 2 and annex (BOE)
- Local Finance Law, Article 82 (BOE)
- Law 20/2007, Self-Employment Statute, Article 38 ter (BOE)
- Italy, Legislative Decree 59/2010, Article 71 (Normattiva)
- Italy, Income Tax Code (TUIR), Article 77 (Normattiva)