Move your business
Where does your company pay less, legally?
A simulation on statutory rates, applied to your figures: company taxes, contributions and personal taxes, side by side for up to three countries, with treaties and the rules that apply when you move.
I move residence and business
Spain compared with Paraguay
Starting point  Spain | Destination  Paraguay | |
|---|---|---|
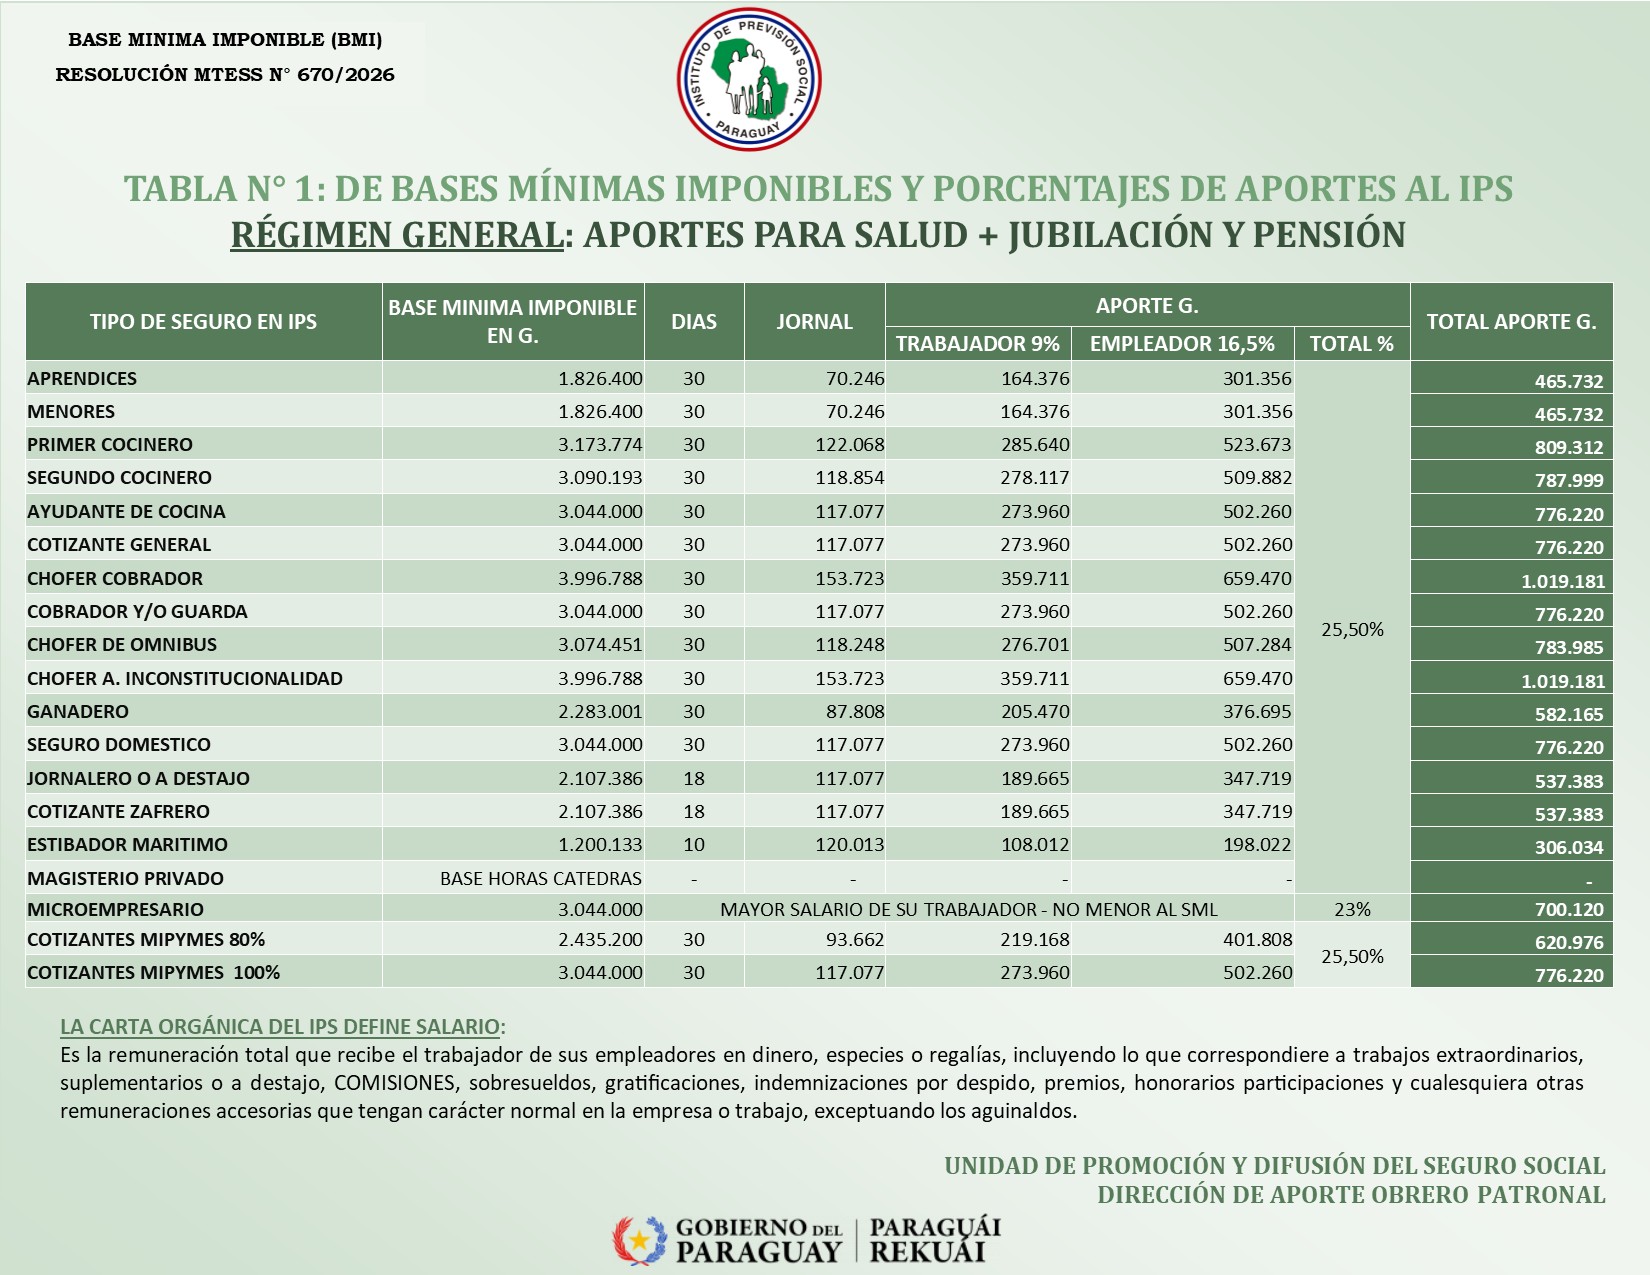
| Employer contributions on staff | €61,300 | €33,000 |
| Contributions on your pay | €6,547 | €0 |
| Corporate taxes | €18,101 | €10,700 |
| Withholding tax on dividends | €0 | €0 |
| Personal tax on dividends | €12,818 | €7,704 |
| Tax due to your country of citizenship | €0 | €0 |
| Personal tax on your pay | €8,951 | €5,709 |
| Total taxes and contributions | €107,717 | €57,113 |
| Total burden on profitTaxes and contributions as a share of profit before them (turnover × margin). | 53.9% | 28.6% |
| Net to you (pay + dividends) | €92,283 | €142,887 |
| Difference from today | €0 | -€50,604 |
What counts before the rates: Spain
The result often depends less on where you go than on the rules of the country you leave.
- Leaving can trigger a tax on the unrealised gain on your shares (exit tax). Not included in the figures. (for Paraguay)
- Your starting country keeps treating citizens who move to this country as residents unless they prove otherwise. (for Paraguay)
Moving residence means moving it for real: where you spend most of the year, your home, your family ties. A registration abroad is not enough on its own.
What the simulation leaves out: deductions and personal allowances, local taxes where no region is chosen, church taxes, wealth taxes, special regimes and incentives. Contributions on your pay follow the country of the company. Rates in force on 17 November 2026.
)
This is a simulation on statutory rates applied to the figures you entered. It is not tax or legal advice.